
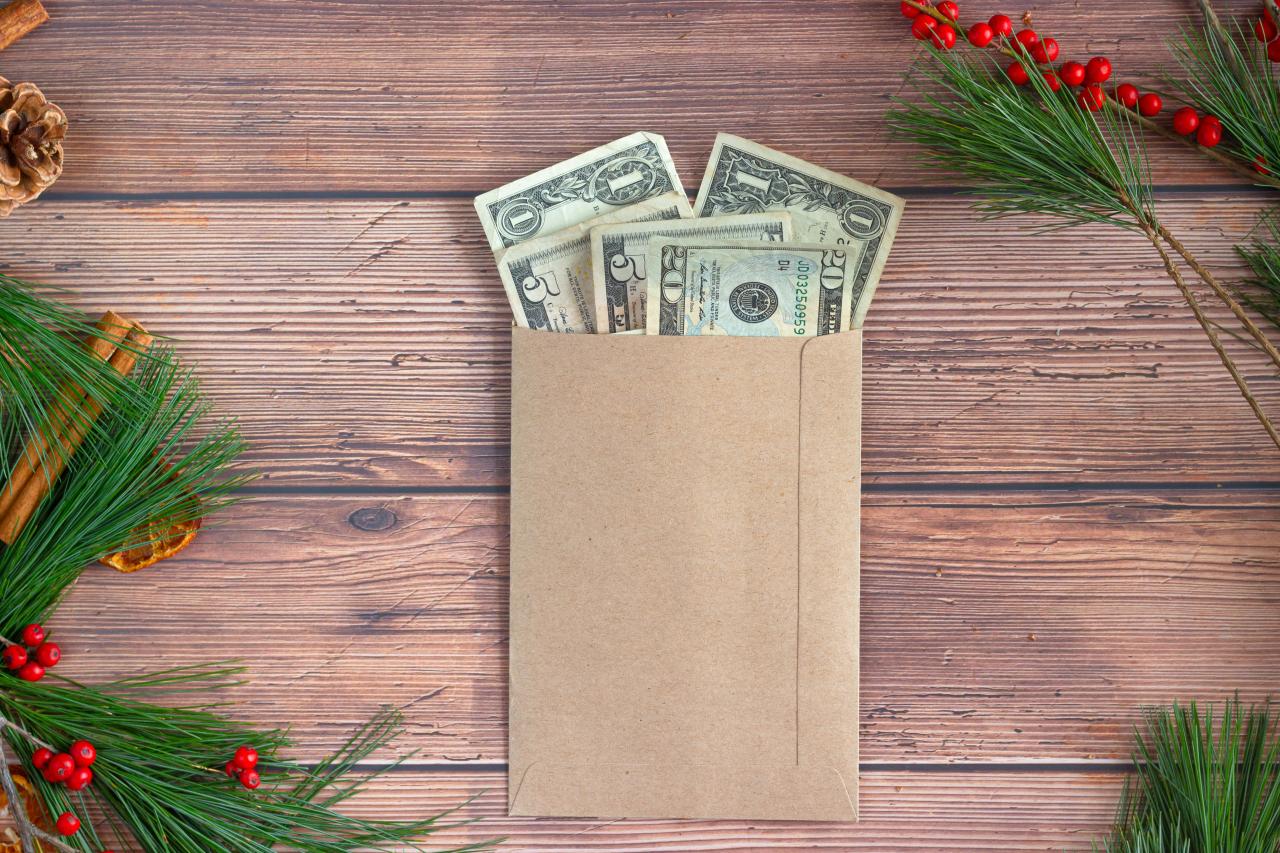
Cash stuffing is an envelope budgeting method: after covering bills and savings, you assign fixed amounts of cash to selected spending categories. Each envelope creates a visible limit. When it is empty, spending in that category pauses or money must be deliberately moved from another category.
Worldwide Google Trends data reviewed on October 5, 2026 showed recurring interest in “cash stuffing” over both 12 months and 30 days. Social media has made the presentation popular, but the underlying idea is older: track spending, separate categories, and receive immediate feedback before a purchase.
Understand What Cash Stuffing Can Do
The method makes variable spending tangible. A digital balance may combine rent, food, savings, and discretionary money in one number. Separate envelopes show what remains for groceries, transport, or entertainment without mental subtraction.
Cash stuffing does not create income, reduce fixed bills automatically, or solve an unbalanced budget. It also should not delay essential payments or minimum debt obligations. Use it as a control for categories where day-to-day choices matter.
Build the Budget Before Filling Envelopes
Calculate take-home income and list fixed obligations, minimum payments, savings contributions, and predictable irregular costs. What remains can be divided among cash categories. Review recent statements or receipts instead of guessing from an ideal month.
Useful categories are specific enough to guide decisions but not so numerous that maintenance becomes exhausting. Groceries, local transport, personal spending, eating out, and household supplies may work. Rent, utilities, online subscriptions, and other electronic payments usually stay outside physical envelopes.
Choose a Funding Schedule
Fill envelopes when income arrives or on a weekly schedule. If 400 currency units are available for groceries over four weeks, an even illustration would allocate 100 per week. That arithmetic does not determine whether 400 is adequate; household size, food prices, dietary needs, and local conditions do.
For irregular income, fund essentials first and use conservative amounts. Avoid withdrawing money needed for upcoming electronic bills. A calendar of due dates helps show which bank balance is already committed.
Photo by Tiffany Tertipes under the Unsplash License.
Record Every Movement
Write the starting amount on each envelope and record spending. Receipts can be stored temporarily, but totals should be updated before they become a pile. If money moves between categories, note the transfer so the system continues to describe reality.
CFPB spending tools recommend collecting receipts, categorizing transactions, and reviewing totals. Cash stuffing adds a spending limit to that tracking process. The feedback is most useful when records are current.
Handle Cashless Spending
Many purchases require cards or transfers. A hybrid system can use physical cash for a few problem categories and digital “envelopes” or ledger balances for everything else. When a card purchase belongs to a cash category, reduce that envelope’s recorded balance immediately and preserve the cash for the card payment.
Do not count the same money twice. Cash in an envelope and an unreduced bank balance can create the illusion that both are available. A simple reconciliation routine after each card purchase prevents this error.
Choose one regular time each week to compare envelope balances, receipts, and account activity. If cash was reserved for a card purchase, move it back to the account before the payment is due or mark it as unavailable. This small routine keeps the physical and digital parts of the budget aligned.
Protect Physical Cash
Cash can be lost, stolen, damaged, or spent by another household member. It may not receive the protections that apply to funds held with regulated institutions. Avoid displaying large balances publicly or storing more at home than the system genuinely requires.
Think about safety while traveling and at the point of sale. Carry only the relevant envelope or a smaller daily amount. Confirm local rules for cash transactions and declarations where applicable.
Photo by Jakub Żerdzicki under the Unsplash License.
Decide What Happens to Leftovers
Set the rule before month-end. Leftover cash might roll forward, build a category buffer, move to an emergency fund, or support a planned goal. Any option can work if it is recorded and does not hide overspending elsewhere.
Do not empty a successful category merely because another category ran out. Moving funds is a real tradeoff. Pause and decide which priority changes rather than making transfers automatic.
Review Whether the Method Helps
After four to eight weeks, compare planned and actual spending. Ask whether purchases became more intentional, bills remained covered, and recordkeeping was manageable. If the method causes missed electronic payments, excessive ATM fees, safety concerns, or constant envelope transfers, adjust it.
A broad framework such as the 50/30/20 budget can set overall direction while envelopes control selected categories. Digital categories may provide the same feedback with less physical risk. The best version is the simplest one you can maintain accurately.
Conclusion
Cash stuffing turns selected budget limits into visible, physical amounts. Build the complete budget first, use envelopes for controllable categories, record every purchase and transfer, and protect the cash. A hybrid or digital version is equally valid when it provides clear limits without risking bills, security, or accuracy.
This article is for general informational purposes only and does not constitute financial, investment, tax, or legal advice. Consider consulting a qualified professional about your individual circumstances.